| ||||||||||||

If you’re trying to balance the costs of employee benefits while maintaining the kinds of offerings employees are looking for, you’ve got a lot to consider. After all, benefits are a key area of competition for attracting talent.
Employee benefits are the non-wage compensation — like health insurance, retirement plans, and voluntary insurance — that employers offer to attract and retain talent.
Topping the employees' lists are healthcare and retirement planning, but they are interested in other products and benefits, too, especially given changes in the workplace environments and requirements over the last few years. (Related: Benefits aimed at a hybrid workplace)
So how can you create an attractive baseline benefits package and still control costs?
Challenges with baseline benefits
In terms of benefits, employees primarily look to their employers for access to health insurance and ways to save for retirement. Yet the trend in both areas is toward consumer-driven products, meaning employees need to make more of their own decisions about what benefits they choose and what they will spend. Gone are the days when the employer could simply offer a "one-size-fits-all" benefits package.
However, many employees really don't want to be driving this bus. They’re focused on their work and careers, they don’t always have the time to research all the choices they have, and they may not understand how to pick the best benefit coverages for their own life circumstances.
Meanwhile, employers may find the situation even more complicated because costs can easily get out of control. That’s why some employers are offering a flat spending credit that employees can use for an array of benefits, or just toward health benefits (medical, dental and vision).
Today, employees have many questions — whether they feel comfortable asking them or not. More than ever, business owners and benefits managers need to understand their employee population’s needs as well as find ways to educate employees about benefit options.
Health insurance
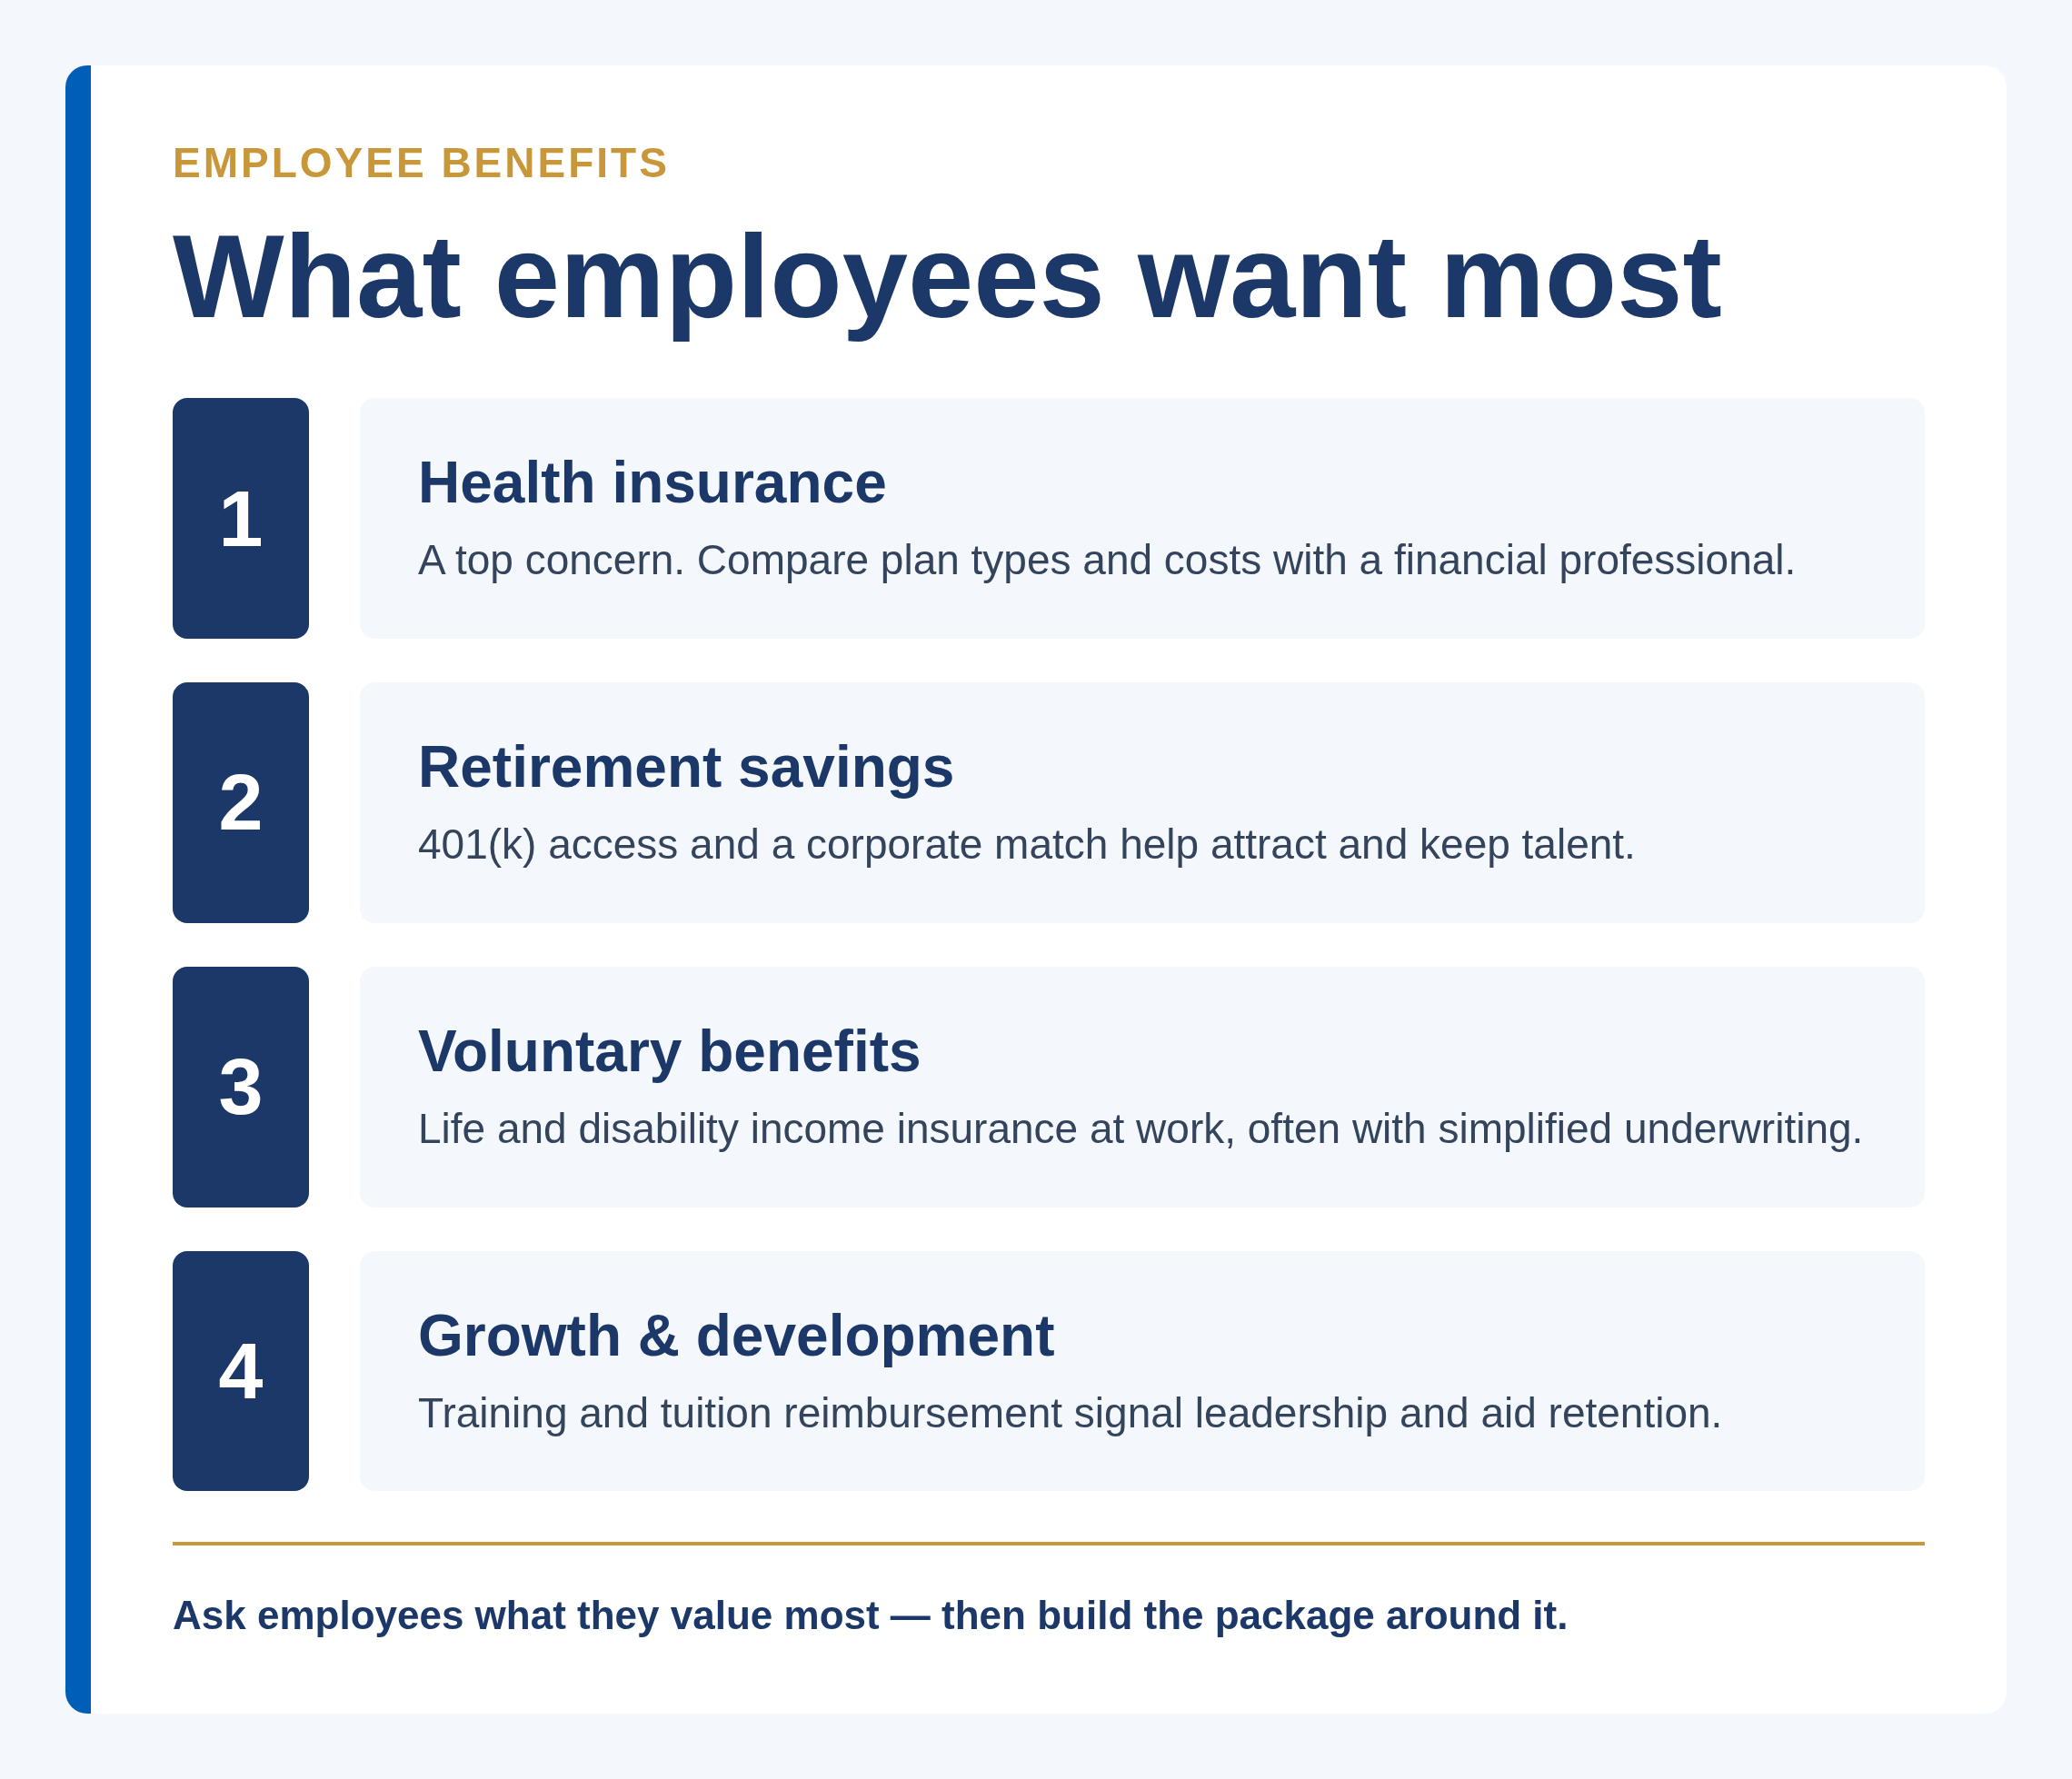
A top concern of employees is health insurance. The marketplace is flooded with plan types and a financial professional can really help employers deconstruct the details.
In general, traditional health plans have higher premiums and fuller coverages, and vary in terms of coverage for in-network versus out-of-network providers.
To trim costs, many employers choose to offer high deductible health plans (HDHPs) because they offer reduced premiums — but, in these instances, employees pay more out of pocket because there are higher deductibles than with traditional health plans. However, these plans also offer employees the chance to reduce their federal taxes by saving for out-of-pocket expenses through a health savings account (HSA).
An HSA is different from a flexible spending account (FSA) — HSA funds can roll over from year to year and stay with the employee, while most FSA funds are use-it-or-lose-it. (Related: Differences between FSAs and HSAs explained)
A financial professional can help you compare your employee population’s needs with the pros and cons of the various plans. They can also check with multiple carriers to compare prices. (Need a financial professional for your business? Let us know.)
Retirement options
The ability to contribute to a qualified retirement plan — 401(k), 403(b) or IRA, for example — is often the second most important benefit employees look for. Offering a corporate match is a great way to attract talent.
For smaller employers, SEP and SIMPLE plans can be simpler, lower-cost alternatives. (Related: SEP or Simple: Which IRA is right for your business?)
When selecting a plan administrator, look for employee resources like call centers, online account management and tools that can help employees plan and manage their retirement funding.
Not all businesses are required to offer their employees retirement benefits. But many businesses find the benefit gives them an edge in recruitment when talent availability is tight. Also, many states have government-sponsored retirement plans with mandatory participation and more may follow suit. (Related: State-mandated retirement plans gain traction)
And, thanks to retirement provisions recently passed by Congress, business owners and employers can offer stronger retirement savings plans to their employees. Indeed, since 2025, certain new 401(k) and 403(b) plans are required to automatically enroll employees, with contributions automatically scaling up. Employees can opt out of either the enrollment or the annual increased contributions, but they will be enrolled by default. (Related: Building better retirement plans with SECURE 2.0)
And offering such plans is getting easier. Legislative changes also increased the ability of employers to band together to create a single retirement plan as opposed to creating separate plans for each business. Such Pooled-Employer Plans can potentially reduce costs, cut regulatory red tape, and limit legal liability for businesses.
Another option to consider is offering a more traditional pension. While it's not very common for smaller businesses, offering one can help ensure employee retention for longer periods of time. A pension that has a defined vesting period, such as five years or more, is a huge financial incentive to stay with a company, especially on top of an employee's 401(k) plan.
Voluntary benefits
Next up are voluntary benefits. These may not cost employers, unless the employer elects to subsidize these benefits as an incentive for employees. Voluntary benefits may give employees the opportunity to take advantage of discounted rates that insurers may offer on certain insurance products provided through the worksite.
For example, critical illness coverage can pay a lump sum if an employee is diagnosed with a covered condition. (Related: What is critical illness coverage?)
Also, when buying life insurance or disability income (DI) insurance through the worksite, employees often times don’t need to go through full medical underwriting. Making insurance products available on a voluntary basis can be a win-win for employers and employees. Employers are offering employees a convenient way to purchase life or DI insurance through the workplace, and employees can get the products they want. Younger workers in particular tend to evaluate employee benefits packages for these options — they want to see they have a range of choices. (Related: Understanding voluntary benefits)
Growth and development
Career and professional development benefits are another important way you can attract and retain great employees. Some employers have development plans that require annual training or supplement employee education with tuition reimbursement. Providing, in some way, for growth and development shows leadership.
Educating employees
Employers are on-point to make information available to employees, especially new hires. To help you, benefit providers have employee communication tools, but keep in mind that everyone learns differently and uses different channels to get information. Employees should be able to opt into the channels they prefer. Information should be available in multiple ways, such as email, webinars, onsite meetings, tools and videos.
Financial wellness programs are an especially important offering for employers offering a robust set of voluntary benefits. Indeed, as retirement and insurance offerings in the workplace grow and become more comprehensive, it’s more essential that employees understand the advantages and implications of their choices.
Bottom line
The best benefits to offer your employees are the ones they want the most. Talk to them. Get to know their needs and concerns. Find out what benefits they’d spend money on and what they wouldn’t.
When you discover what’s really important to them, you may even consider picking up the tab for some of it. When you look at both the cost to the business and potential tax advantages you may receive, additional benefits may cost you less than a salary raise and have the same positive effect on the employee.
Since 1851, MassMutual has been focused on helping people secure their financial future and protect the ones they love. That mission is why we have thousands of financial professionals to assist you on your journey through insurance, investing, retirement planning, estate management, and more.
_________________________
Frequently Asked Questions about employee benefits
Q. What benefits do employees want most?
A. Employees consistently rank health insurance and retirement savings plans, like a 401(k), at the top of their wish list. Voluntary benefits such as life and disability income insurance, plus growth and development opportunities, round out the package.
Q. Is a small business required to offer a retirement plan?
A. Not all businesses are required to offer retirement benefits, but many states now mandate employer participation in a state-sponsored plan if no qualifying plan is offered. Offering a plan can also give small employers an edge in recruiting.
Q. What are voluntary benefits and do they cost the employer?
A. Voluntary benefits let employees buy insurance — such as life or disability income insurance — through the workplace, often at discounted rates and with simplified underwriting. They typically cost the employer nothing unless the employer chooses to subsidize them.
________________________
Discover more from MassMutual ...
Employee retention: 3 key points
The bonus that keeps giving: Insurance
Employee financial wellness: Have a game plan
This article was originally published in September 2017. It has been updated.
_______________________________________