| ||||||||||||

It’s a common question regarding traditional individual retirement accounts (IRAs): Should you pursue a Roth conversion?
In a Roth conversion, the IRA owner takes a distribution from their traditional IRA, pays income tax on the distribution, and rolls the funds into a Roth IRA. For the year of the conversion, the owner will have a larger-than-normal income tax bill. Once the conversion is made, however, it is likely that all future distributions will be income-tax free. If one can afford the tax payment using non-retirement dollars, this technique becomes even more impactful. And unlike direct Roth contributions, there are no income limits on who can convert.
Why do people pursue this strategy? Typically, there are two motivating factors:
1. Market performance is down year to date, which lowers the taxable value of the conversion.
2. An expectation of higher income tax rates in the future.
Other factors to consider are the percentage of Social Security on which someone will need to pay income tax in the future and lessening the income tax impact on the next generation. (Related: When to file for Social Security)
All of these are valid points. However, in running the numbers, in many cases there is not a distinct advantage to either a Roth conversion or leaving the assets in a traditional IRA. As such, the determination really comes down to when the IRA owner wants to pay income tax on their IRA, either now or in the future.
Many opt to consult a financial professional to help determine whether or not a Roth conversion makes sense.
Connect with a MassMutual financial professional
The following are some points a financial professional is likely to raise when contemplating a Roth conversion:
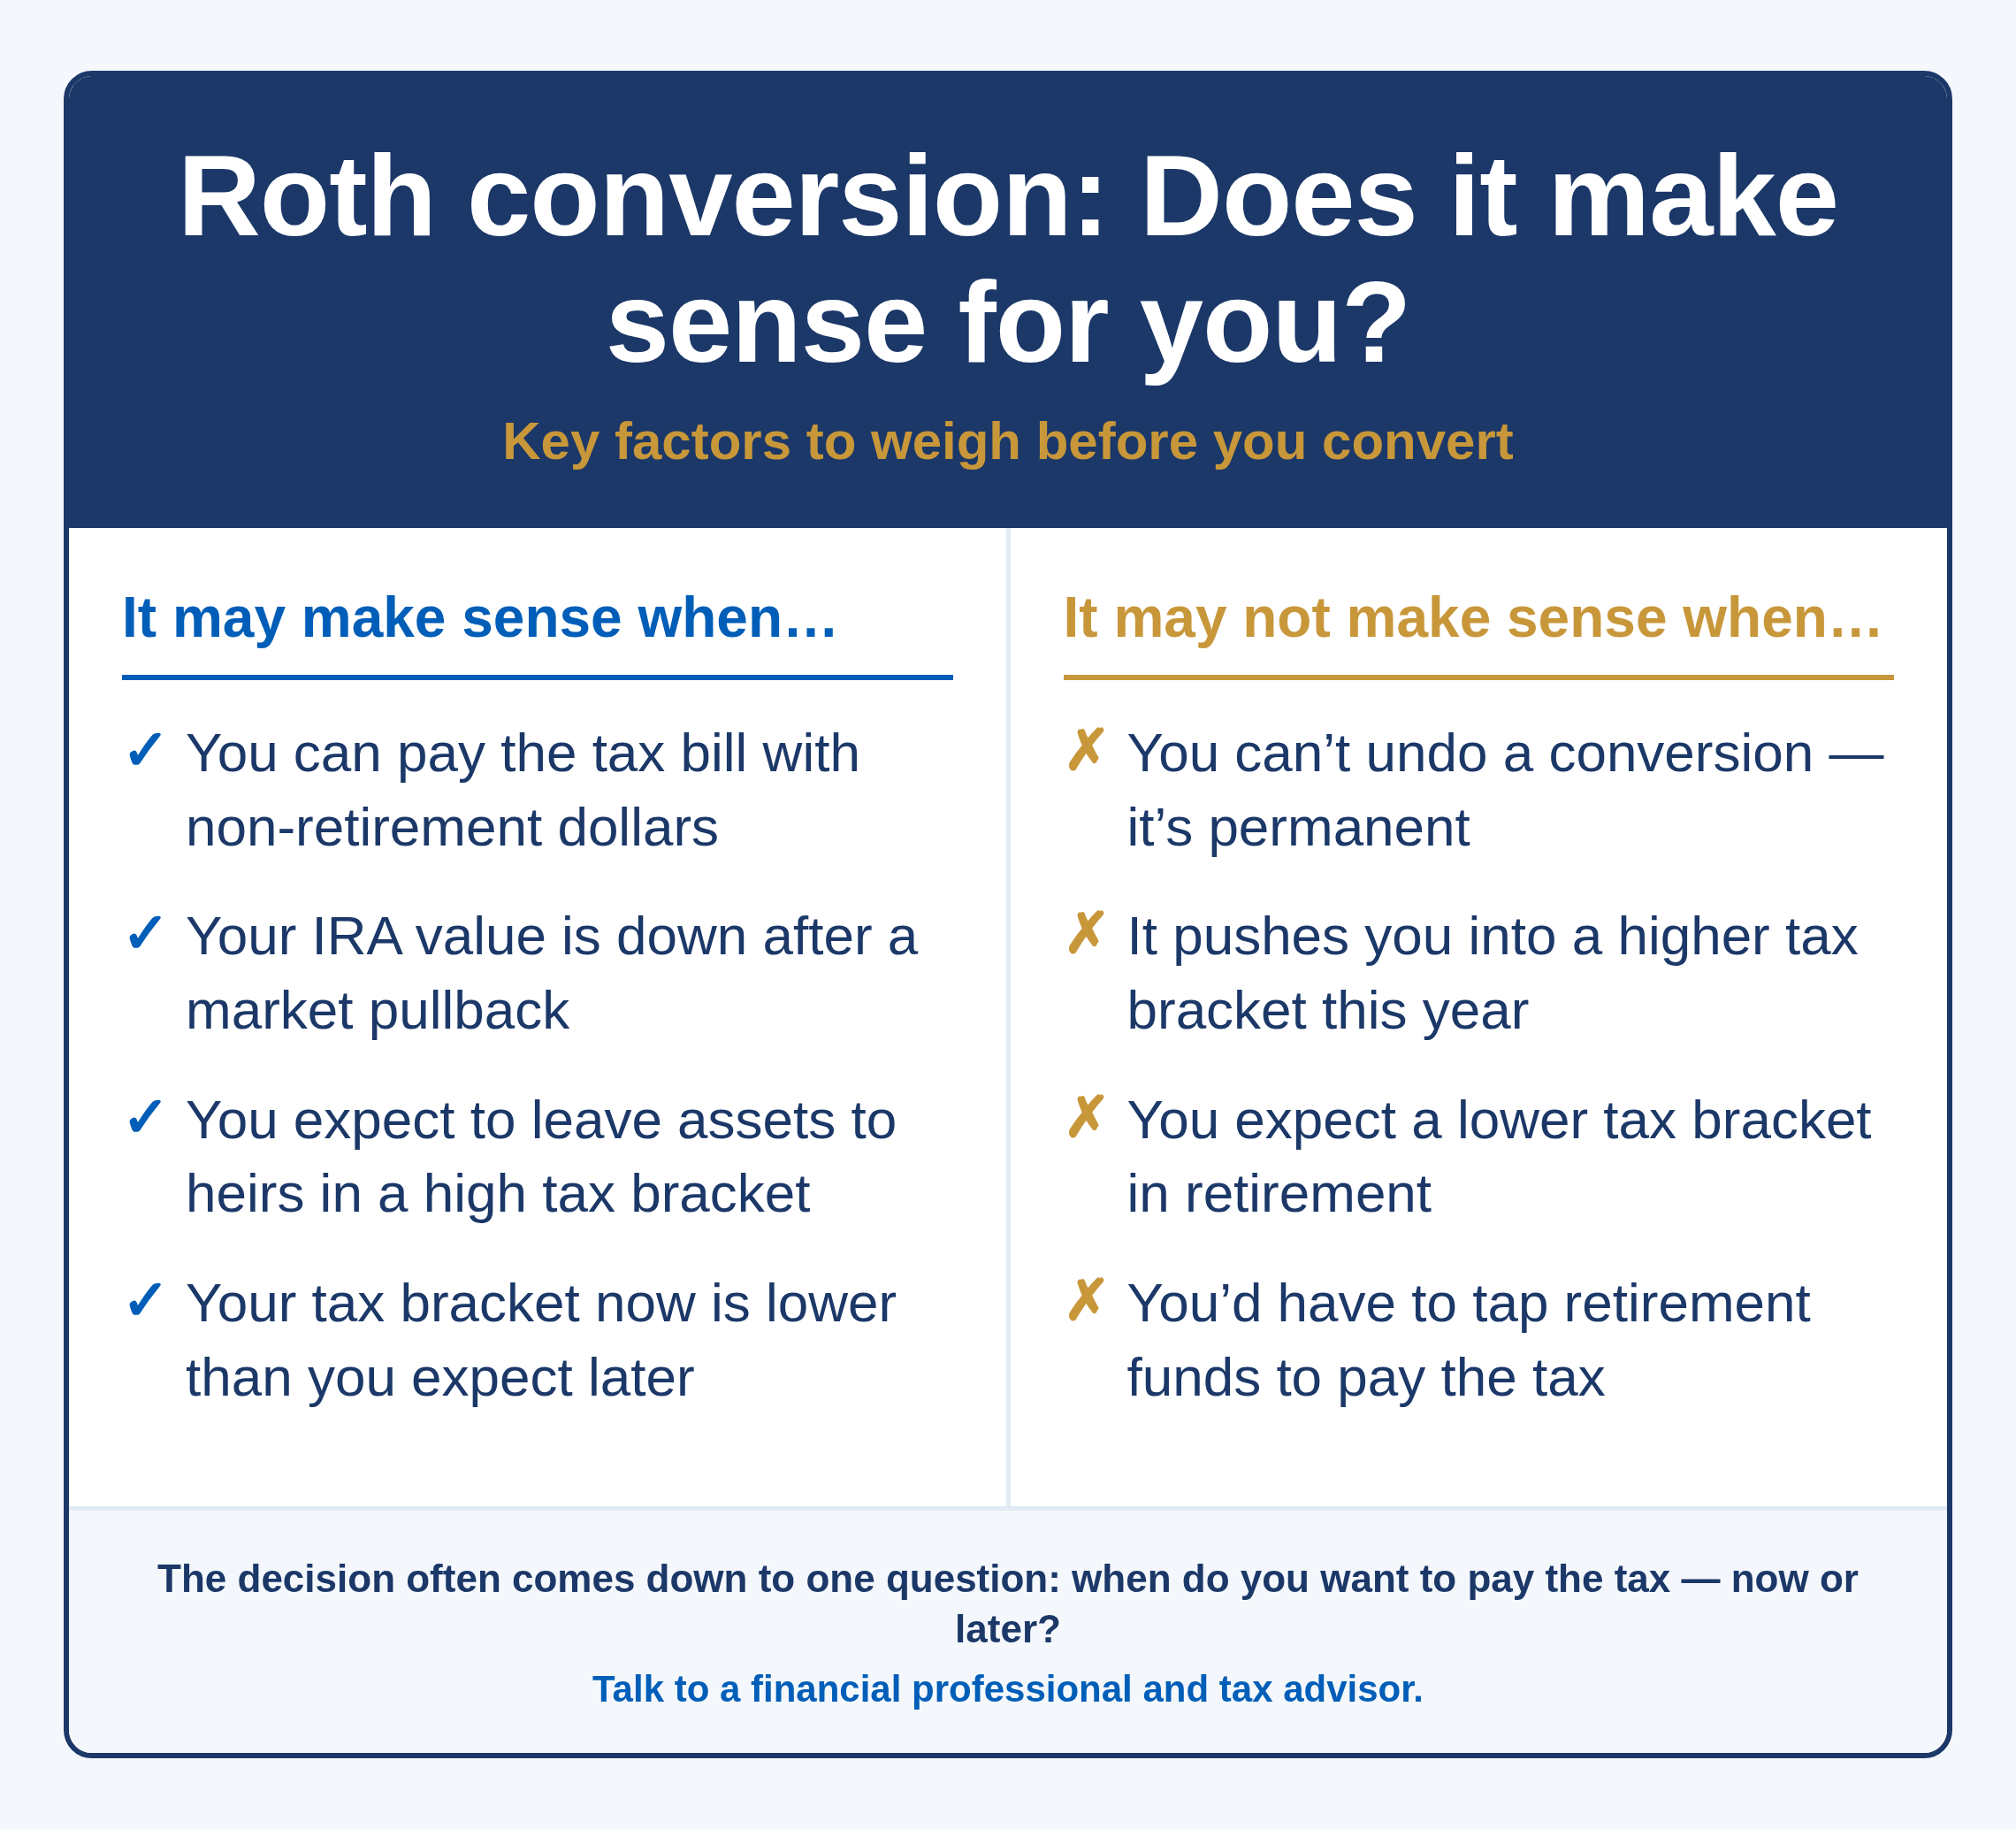
Reasons a Roth conversion may make sense:
- The account owner can afford the tax liability from the Roth conversion without using dollars from retirement funds. (The account owner should avoid making tax payments from converted funds.)
- The IRA market value is down due to a market pullback, and, therefore, there is less taxable income generated.
- The account owner plans to leave the funds to their children and expects the children to be in a high tax bracket.
- A desire to ease the tax burden on heirs, who now generally must empty an inherited IRA within 10 years.
- The account owner’s income and tax bracket in the year of conversion are lower than what they expect in future years.
Reasons a Roth conversion may not make sense:
- One cannot recharacterize the conversion (i.e. if Roth conversion assets depreciate in value AFTER the conversion, the account owner still must pay tax on the value of the assets at the time of conversion).
- The conversion moves the account owner into a higher tax bracket in the year of conversion.
- The account owner expects to be in a lower tax bracket in retirement (i.e.,less income in retirement or the owner expects to move to a state with lower or no income tax, etc.)
- The account owner needs to use dollars from retirement funds to pay income tax on the Roth conversion.
Other considerations:
- Time horizon — A longer time horizon generally means the account owner can benefit from a longer period of tax-free earnings accumulation. During the account owner’s lifetime, there are no required minimum distributions (RMDs) from Roth IRAs. RMDs from traditional IRAs generally begin at age 73 (rising to 75 in 2033), which is one reason some pre-retirees convert before that milestone. (Related: RMDs explained)
- RMDs cannot be converted to a Roth IRA.
- The one-rollover-per-year limit does not apply to Roth conversions, thereby allowing for the conversion of smaller amounts over two years (but within 12 months), if desired, in order to spread the tax liability. Many financial professionals recommend spreading conversions over several years to smooth the tax hit.
The following case study, based on an actual client situation, helps to illustrate the application of the competing factors listed and discussed above.
Weighing Roth conversion: An example
A client (age 63) had recently retired and was transitioning from high W-2 wages to a mix of investment and retirement income. His spouse was also age 63.
The question was three-fold:
1. Should the client and spouse convert their traditional IRAs to a Roth IRA?
2. If yes, when should they begin to convert?
3. Should both convert or just one?
A few more details:
- Husband’s IRA market value: $1.3 million
- Spouse’s IRA market value: $162,500
- Nonqualified assets: $3,500,000
In evaluating this case and hammering out the numbers in the Roth conversion window, there were some assumptions about investment growth (7 percent annually) and inflation (3 percent).
What the projected numbers bore out was interesting:
- If the client and spouse decided to convert, with a lower market value due to investment markets being down 10-20 percent that year, the overall tax due was $492,000 versus $519,000 if they decided to wait until the next year. The tax due in that coming year was higher due to an assumption that the accounts would recoup some losses from the first part of the year.
- However, if they waited until the next year, with the assumption of better market performance, at their combined life expectancy, there was a possibility of an additional $700,000 or so available for their remainder beneficiaries.
These, of course, were illustrated projections and not guarantees. But they helped frame the factors in the decision. Ultimately, the client and his spouse decided to revisit at the end of the current year, and with the projections working out, they decided to convert in the next year.
Conclusion
When weighing the conversion question, evaluating the numbers is important. It’s also important to make informed decisions and keep in mind that conversion may not make sense. That’s why it’s usually helpful to have a conversation with your financial professional and tax advisor. That can help clarify what the considerations mean in terms of your financial goals as well as any needs for planning for a surviving spouse and/or future generations.
______________________________________
Frequently Asked Questions about Roth IRA conversions
Q. What is a Roth IRA conversion?
A. It's the process of moving money from a tax-deferred retirement account, like a traditional IRA, into a Roth IRA. You pay income tax on the converted amount in the year of the conversion, but future qualified withdrawals can be tax-free. (Related: Pros and cons of Roth IRA conversions)
Q. Can I undo a Roth conversion if the market drops afterward?
A. No. Since 2018, Roth conversions cannot be recharacterized or reversed, so you'll owe tax on the value at the time of conversion even if the assets later decline. That's one reason timing and dollar-cost-averaging conversions over several years can help. (Related: When to do a Roth conversion and when not to)
Q. Is there an income limit for Roth conversions?
A. There's no income limit on conversions, unlike direct Roth IRA contributions. That's why high earners often use conversions as their way into a Roth IRA. (Related: Pros and cons of Roth IRA conversions)
Discover more from MassMutual…
DIY planning for retirement with IRAs
Stretch IRA? Four possible alternatives
Calculator: What is my required minimum distribution?
_________________