| ||||||||||||

Your 401(k) retirement plan provides a number of important benefits: pretax contributions that lower your taxable income, tax-deferred growth potential, higher contribution limits than an IRA, and even, in some cases, an employer match.
But simply funding your 401(k) through regular payroll deductions is not enough. If you hope to reach your retirement goals, you must keep tabs on how your account is performing, how your investments are allocated, and how much you surrender in annual fees.
Enter the 401(k) statement.
While many investors leave their quarterly 401(k) statements unopened, these account summaries offer critical insights that can help ensure that their savings stay on track.
“I think it's safe to assume that most people don't read or fully understand their 401(k) statements,” said Ricardo Diaz, head of Blueprint Income in Boston, Massachusetts, citing financial literacy and time constraints as contributing factors. “Many individuals find these documents intimidating, overwhelming, or confusing, especially if they don't have a background in finance. As a result, some people may skim over their statements or avoid them altogether.”
To help retirement savers take control of their financial future, we’ve broken down the essential elements of a typical 401(k) statement:
Here’s a closer look at each of these factors and why they matter.
Connect with a MassMutual financial professional
What is a vested account balance in a 401(k)?
While no two 401(k) statements are exactly alike, it’s safe to assume that your account balance, which reflects the amount of money you have accumulated in your account so far, will be front and center.
Your statement will call out your “beginning balance,” or the amount of money your account started with at the beginning of the statement period (quarterly or annual), and your “ending balance,” or the amount of money you have at the end of the statement period.
Your account information may also tell you how much you personally contributed during that period from payroll deductions and how much your employer contributed, if they offer matching. (Many employers will match employee contributions up to a certain percentage. (See How to set up your first retirement plan)
And it will generally reveal what portion of your 401(k) balance is vested, meaning, owned by you. Many employers use a vesting schedule in which employees gradually accumulate ownership of any matching employer contributions to their retirement plan — typically over a three-to-six-year period. When you are fully vested, the employer contributions are yours to keep even if you leave your job. You always own the contributions you make to your 401(k) plan.
By adding up your balances from all your retirement accounts, including any IRAs you may have or retirement plans still invested with a former employer, you can determine pretty quickly whether you’re roughly on track to retire.
There are dozens of rules of thumb that offer guidance on how much you should have set aside for retirement by every age. (Related: 6 common financial rules of thumb to guide your planning)
For example, some suggest you should have:
- About ½ to 1½ times your annual income saved by age 30.
- About 2 to 3 times your annual income saved by age 40
- About 5 to 6 times your annual income saved by age 50.
If your balance is less than such targets, you may need to take action.
- Consider contributing more to your retirement account to shore up your savings.
- You may also choose to adjust your investment holdings to assume slightly more risk in an attempt to potentially increase future returns.
- Or, you may need to push back your target retirement date to ensure that you don't outlive your savings.
A financial professional can help you create a customized plan that aligns with your unique goals, time horizon, and tolerance for risk. (Related: 4 simple ways to become a super saver)
Performance
Your annual 401(k) statement should also tell you your rate of return for the quarter, year to date, and potentially over the last 12 months. Most statements that you access using a digital device also enable participants to access their annualized rate of return since their initial contribution.
Many such digital offerings also provide research tools that let you compare the performance of your underlying investments to that of its peers, or to a benchmark in the case of an index fund.
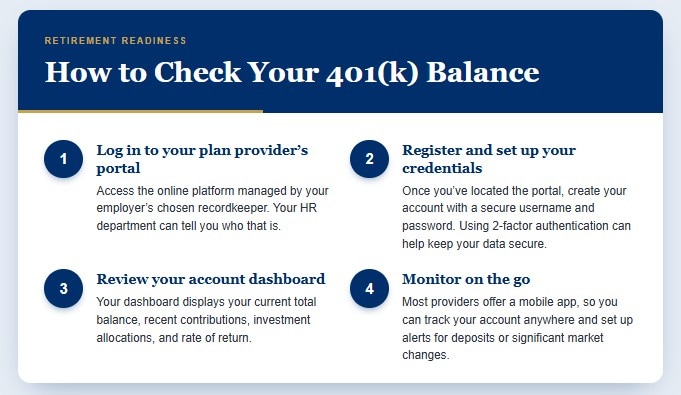
Historically, many financial planners suggest that retirement savers with a balanced portfolio can expect to realize an average annual rate of return for their 401(k) of 5 percent to 8 percent over the long term, but your actual return can be higher or lower depending on market fluctuations and how your investments are allocated.
Here again, a financial professional can help you determine the ideal rate of return to reach your retirement goals.
Asset allocation
Another important section on your retirement account statement is your asset allocation, a percentage breakdown often expressed as a pie chart that tells you how the investments within your account are allocated across asset classes, including stocks, bonds, and cash.
If you’re accessing your statement via mobile phone app or your computer, it may be necessary to select a link that invites you to review and change your investment elections.
By managing your asset allocation, you may be able to help maximize your returns while minimizing risk. (Learn more: Asset allocation and diversification: Do you know where your financial eggs are?)
A balanced portfolio that is tilted more heavily toward stocks has the potential to produce higher returns, but it also typically involves greater risk. Some investors who have fallen behind on their savings may be willing to accept that higher risk in exchange for upside potential, although higher returns are never guaranteed. (Learn more: Investor profile: Are you aggressive?)
Conversely, a portfolio that primarily consists of bonds, especially high-quality government bonds such as Treasurys, is likely to deliver lower returns, but may also reduce your level of risk. Many investors increase their exposure to bonds as they approach retirement, as they no longer have the time horizon to recover from a major market downturn. (Learn more: Investor profile: Are you conservative?)
Be aware that, over time, the ebb and flow of market performance will cause certain segments of your portfolio to outperform (or underperform) the others, causing your asset allocation to drift. That reduces downside protection and may result in lower returns. By keeping watch over your asset allocation, you will be better prepared to rebalance your portfolio periodically to help ensure that your savings stay on track.
Many employers offer target-date funds among their 401(k) investment offerings, which can help take the guesswork out of managing your asset allocation. Target date funds automatically adjust their split between stocks and bonds, becoming more conservative as you age. But they can potentially be too conservative depending on your tolerance for risk and objectives. A financial professional can help you determine whether your investment choices might help you reach your goals.
Fees
Unbeknownst to many retirement savers, your 401(k) plan isn’t free. It includes administrative fees and expenses, which can affect your annual returns and future retirement income.
- Your expense ratio is the cost of owning your mutual fund or target-date fund, expressed as a percentage of assets.
- Administrative or recordkeeping fees are charged by the plan sponsor for managing the plan, typically shown as a flat dollar amount that gets deducted quarterly.
- And the advisor fees are what you pay if a financial professional managed the plan on behalf of your employer.
A 2026 survey by 401(k) rollover firm Capitalize found that 71 percent of 401(k) holders said they did not know how much they were paying in annual fees.1
Nearly half of Americans surveyed estimated they were paying less than half a percent (0.5 percent) of total assets in 401(k) fees and costs — but only 10 percent of all plans charge less than 0.4 percent.
“The unfortunate reality is that paying higher 401(k) fees than you need to can add years onto your working life,” the survey authors wrote. They provided an example:
Imagine two people, both of whom are 25 years old, earn $100,000, and will be ready to retire as soon as they’ve personally amassed $1,000,000 in retirement savings.
Person A invests $10,000 annually into his 401(k) plan on a pre-tax basis and is able to earn an average of 8 percent on his investments. The investments available in his 401(k) plan are expensive, though, and average a cost of 2 percent annually. As a result, Ryan’s net annual return is 6 percent (8 percent gross return minus 2 percent in expenses). Assuming these variables, he can expect to retire at age 58.
Person B is the same age, earns the same salary, achieves the same 8 percent average return, and makes the same 401(k) contributions. However, they elected to invest in lower-cost options in their 401(k) plan, paying just half a percent (0.5 percent) annually in total fees. As a result, their net return every year is 7.5 percent (8 percent – 0.50 percent). Assuming these variables, they can plan to retire at age 54. That’s 4 years earlier than Person A.
The fees you pay are more likely disclosed on your annual 401(k) statement, rather than your quarterly statements. They should also be disclosed when you choose or change your investments. If you can’t determine your fees and expenses, ask your employer to provide it.
Investment fees are much more transparent now than they once were, said Ken Lloyd, an investment specialist with Commonwealth Financial Group in Quincy, Massachusetts.
“If your fund is returning 11 percent, but your total fee is 1 percent, your net return is 10 percent,” he said. “It’s important to understand and review your fees because it makes a big difference in what goes into your pocket.”
Beneficiary elections
Another entry on your 401(k) statement is your beneficiaries. It is critical that you review your retirement plan beneficiaries periodically, and always after a major life event including a birth, death, divorce, or new marriage. (Learn more: Common beneficiary mistakes)
Why? Whoever is named as beneficiary to your retirement accounts is legally entitled to that money when you die, even if it differs from the beneficiaries named in a more recent will.
You do not want what may be your biggest asset being left to an ex-spouse or a relative who may be prone to financial recklessness, if that’s no longer your intent.
Conclusion
Saving for retirement is a critical step toward financial independence. To meet your goals and ensure that you don't outlive your savings, however, you must also monitor your accounts to make informed decisions and be sure that your savings stay on track. Your 401(k) statement can help.
“While each individual account contributes to your financial well-being, it's the collective picture that matters when it comes to achieving a comfortable retirement,” said Diaz. “Your 401(k), IRAs, taxable investment accounts, and other savings vehicles are different pieces that are required to work together to reach your retirement goals. Circumstances change: your retirement goals, risk tolerance, and financial obligations may evolve over time. By regularly assessing your financial landscape, you can identify potential gaps, rebalance your portfolio, and adjust your savings contributions to ensure that they align with your aspirations.”
A financial professional can help you answer questions and keep you on track.
________________________________
Frequently asked questions about reading a 401(k) statement
Q: What fees should I look for on my 401(k) statement?
A: Your 401(k) statement may reflect three types of fees: expense ratios, administrative or recordkeeping fees, and adviser fees. A 1 percent difference in total fees can reduce your final balance by 28 percent over a 35-year career, according to the Department Labor.
Q: What is a target-date fund on a 401(k) statement?
A: A target-date fund (TDF) is a type of investment that automatically adjusts its mix of stocks, bonds, and cash based on your expected retirement year. The year in the fund’s name — for example, “Target Retirement 2050” — is the approximate year you plan to retire. TDFs shift from more aggressive investments (higher stock exposure) to more conservative investments (higher bond exposure) as you approach retirement, following what’s known as a “glide path.”
Q: How often should I review my 401(k) statement
A:Generally spe?aking, you should review your 401(k) statement at least once per quarter when it arrives — and more often if you have experienced a major life event such as a marriage, divorce, job change, or the birth of a child.
_______________________________________
Discover more from MassMutual…
5 potential retirement obstacles to watch out for
Cut the clutter in your finances
Need a financial professional? Find one here
________________________________________
This article was originally published in September 2023. It has been updated.
1 Capitalize, "Survey: 2 in 3 Americans are in the dark about their 401(k) fees," 2026.


