
| ||||||||||||

You insure your most valuable assets like your home, your car and your life. Most people would agree that they’re worth protection; however, disability income (DI) insurance is something people tend to be less certain about. They’re not sure if they really need it, or if it’s worth the cost. So, is it? There’s no cut-and-dried answer, but there are some strong arguments to be made in favor of DI.
What are the chances you’ll need it?
When you think about the kind of disability that could keep you from working, usually the first thing that comes to mind is a car accident or other catastrophic injury — in other words, something that could happen, but most likely won’t. (Learn more: Disability surprises)
In reality, the most common cause of disability is illness, not accidents or injuries.
Arthritis, back pain, neurological problems, and cardiovascular illnesses are all more common than injuries when it comes to disability claims.1
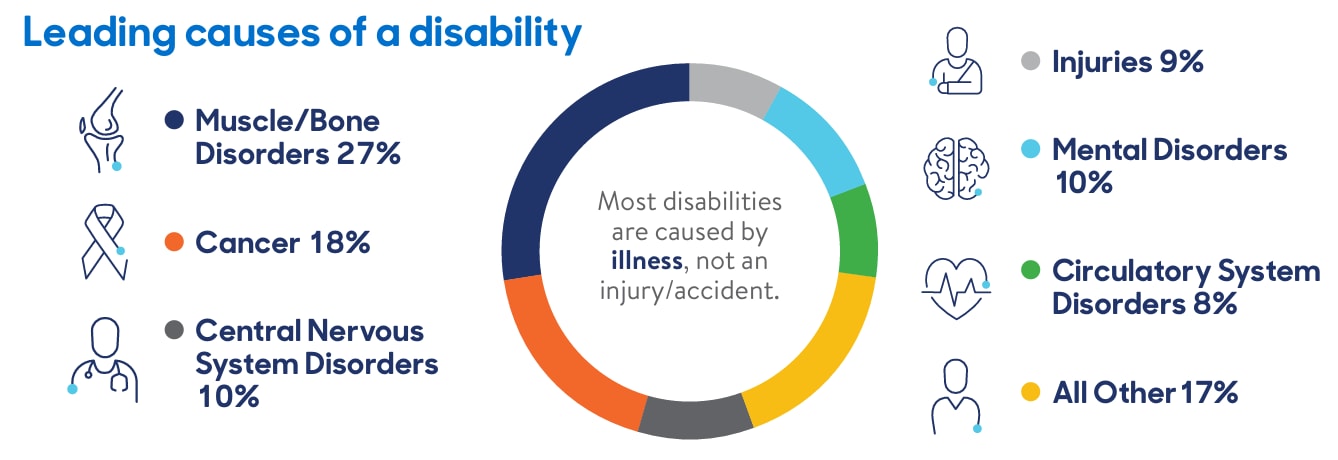
Source: MassMutual claims 2005-2025
Indeed, one in four 20-year-olds will become disabled before reaching retirement age, according to the Social Security Administration.2
You might be thinking that there’s always savings. If you have enough money in the bank to cover your living expenses for more than a month or two, you’re in better shape than the large majority of Americans. If you don’t, you’d need to consider another option.
Also keep in mind that the average disability lasts a lot longer than the one-to-two month range. In fact, the average length of MassMutual disability claims is more than 48 months. Most people’s savings would run out long before that.
Can I afford disability insurance?
Disability income insurance helps replace a portion of your income if you are too sick or injured to work. Many people have DI insurance through their employer. Such coverage, however, can fall short in both the amount and type of coverage your household may need. (Related: 6 ways group disability income insurance may fall short)
There's also Social Security Disability Insurance, but it's designed only for total disability and can be difficult to qualify for. (Related: Social Security disability benefits: A lifeline for many but not for all)
Individual disability income insurance plans can help ensure you have protection that’s right for your circumstances. This is especially important if you're self-employed, since you don't have access to employer-provided group coverage.
But when you’re already paying for other kinds of insurance — home, auto, life, etc. — it’s hard to think about buying more. But a good way to frame it is what disability insurance costs versus what the benefit would be if you used it.
Here’s a hypothetical example:
- Say a 30-year-old man, taking home $56,250 a year buys a disability income insurance policy that costs him $929 per year. (By comparison he could be spending $1,285 a year on a daily coffee, assuming an average price of $3.52.)
- If he becomes totally disabled, after a 90-day waiting period he could receive $4,050 a month over 12 months, replacing about 86 percent of his pre-disability, after-tax income — and hopefully allowing him to keep up his coffee habit.
There are, of course, some limitations and eligibility requirements for DI. So, in the end, it’s a matter of whether you feel like the benefit you could receive outweighs the cost of premiums and the uncertainty that comes with not having any coverage at all. (Related: Why high earners still need disability income insurance)
Costs and benefits vary from policy to policy. Many policies also cover partial disabilities, which can pay a reduced benefit if you're able to work but earn less due to illness or injury.
Protecting your most valuable asset
With any luck, you’ll never have to deal with a disability that keeps you from being able to work. But it’s a good idea to have a plan in place, so that if you ever did become disabled you could still cover your expenses and provide for the people who count on you.
__________________________________
Frequently Asked Questions about disability income insurance
Q. What is disability income insurance?
A. Disability income insurance replaces a portion of your income if you become too sick or injured to work. It helps you cover everyday expenses like your mortgage, groceries, and bills when your paycheck stops. (Related: How to make a disability income insurance claim)
Q. How much does disability income insurance cost?
A. The cost varies based on factors like your age, occupation, health, and the amount of coverage you choose, but it's often more affordable than people expect. A typical policy might cost 1–3 percent of your annual income.
Q. Isn't disability coverage through my employer enough?
A. Employer-provided group disability insurance is a valuable benefit, but it often replaces only a portion of your base salary and may have benefit caps that leave high earners under-protected. Individual disability income insurance can help reduce those gaps.3 (Related: The reality of workplace disability income insurance)
_______________________
Discover more from MassMutual…
Baseball and the longevity threat
The Lottery: Waiting for magic?
This article was originally published in October 2016. It has been updated.
_________________________________________________
1 Social Security Administration, “Annual Statistical Report on the Social Security Disability Insurance Program, 2024,” December 2025.
2 Social Security Administration, “Disability Facts.”
3 Individual disability income insurance does not coordinate with group long term disability insurance. Claim decisions are rendered independent of each other.


