| ||||||||||||

Many people going through the emotional and legal turmoil of divorce may want to “just get it over with.” This can make it easy to overlook or put aside critical financial aspects that can have a lasting impact on your future financial wellness. A divorce financial checklist can help keep these items in mind.
These considerations go beyond the cost of the divorce process itself — ranging by some estimates from $150-$2,000 (DIY or uncontested) to more than $20,000 (contested) for attorney and court fees — and alimony or child support obligations.
So, before signing the final decree, consider these realities.
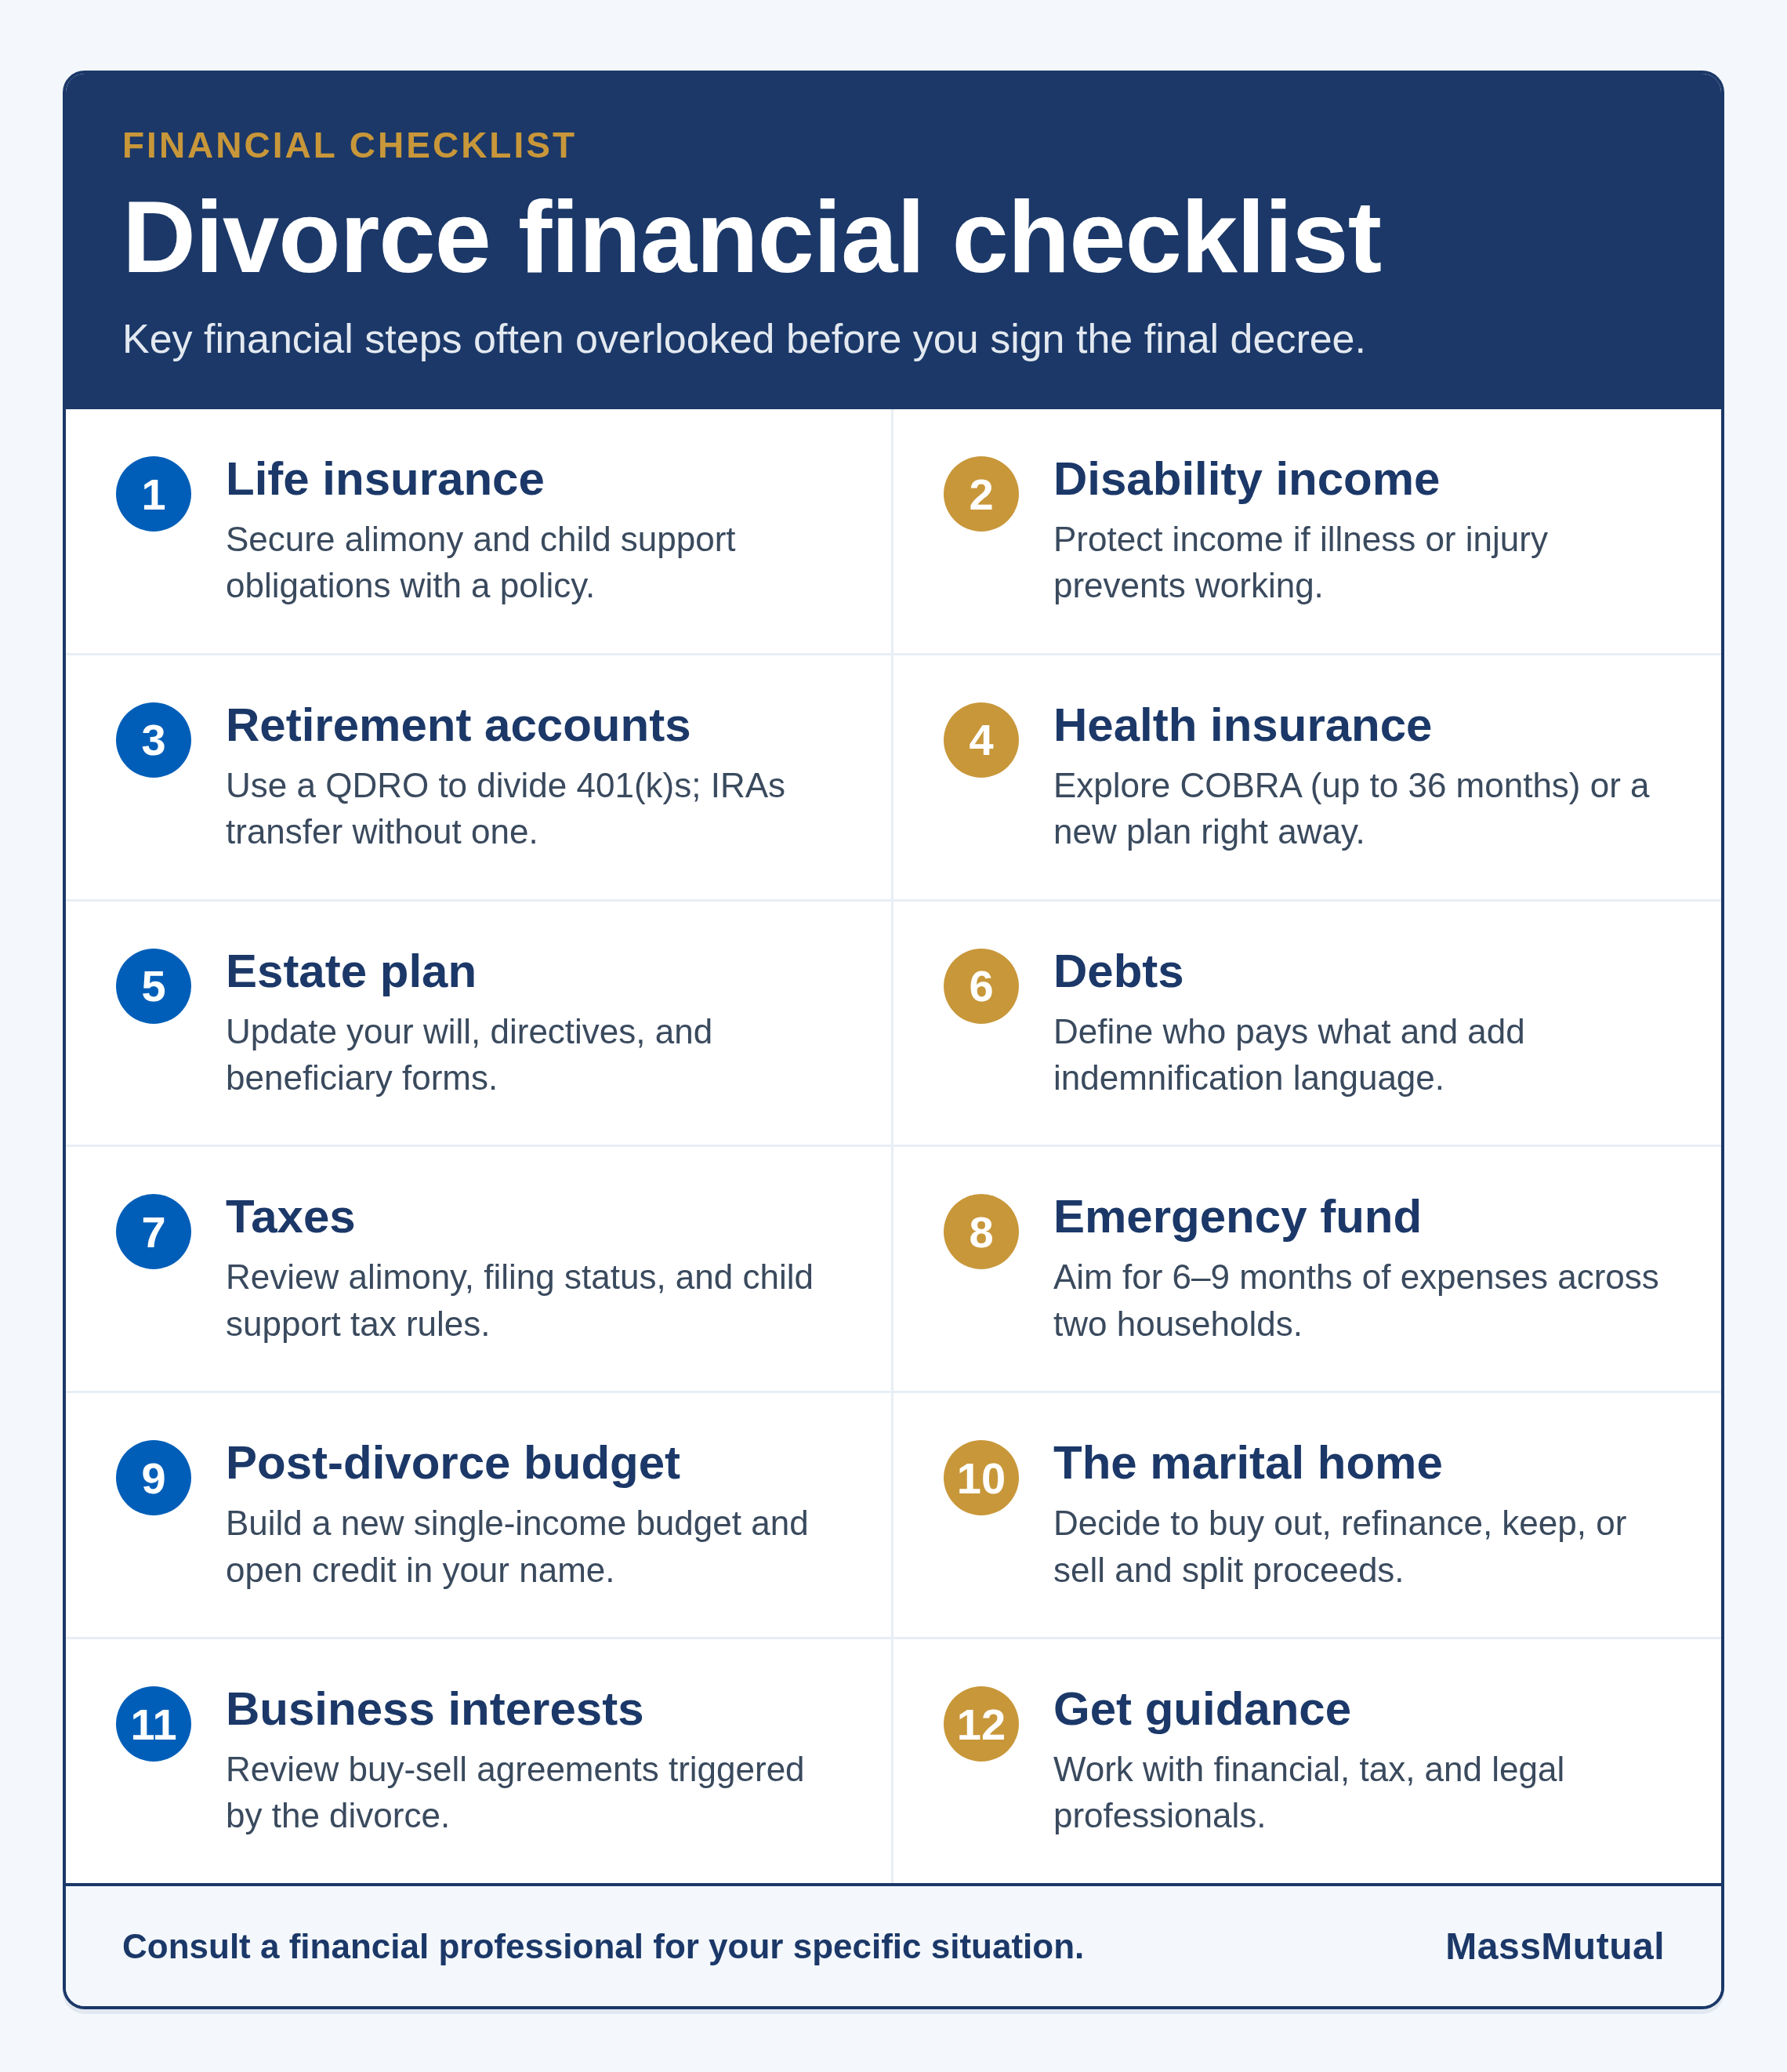
Here is a closer look at each.
Life insurance: Protecting your loved ones
Start with these questions:
- Is one of the divorcing partners the major breadwinner for the household?
- And will they be making alimony payments?
- What happens to that income if something happens to them?
- And will children have to be provided for if a caregiving parent passes away?
That’s why life insurance should be considered as part of the divorce settlement. In fact, it’s often a standard part of any divorce proceeding.
Typically, such a consideration will require one or both parties to maintain a life insurance policy with a certain amount of the death benefit payable to the other party either for the benefit of that party or for the benefit of their children.
There can be further stipulations as well, depending on circumstances. For example, some states automatically remove ex-spouses as beneficiaries, regardless of need. So, divorce settlements can compensate, provided both parties agree. For instance, in some mutually agreed-to settlements, an individual is required to maintain their former spouse as a beneficiary only for the amount of the death benefit specified in the judgment; the individual is then able to maintain another person for any remaining death benefit of the life insurance policy. 1 (Learn more: Divorce and life insurance policies)
“It is essential that a person going through a divorce obtain the ‘right’ amount of life insurance to not only comply with their obligations pursuant to the divorce, but to further protect their loved ones, including a subsequent spouse or children,” said Kelly L. Sidgwick, Esq., of Goldman & Sidgwick, LLP, a family law practice in Natick, Massachusetts.
When thinking about whether the coverage amount of your life insurance policy is still sufficient to meet the needs of your beneficiaries:
- Consider future expenses: Calculate your dependents’ future financial needs, including living expenses, education costs (especially college), and any outstanding debts.
- Get guidance: If you're unsure about the appropriate coverage amount, consider consulting a financial professional. A professional can provide much needed clarity to help you determine the right amount based on your specific circumstances.
While reviewing life insurance needs, you may also want to review your beneficiaries on any current policies you may have, either individually or through your work. Some states automatically remove ex-spouses as beneficiaries. But many others don’t and sometimes an ex is left as a beneficiary on an old policy, leading to undesired outcomes in the future. (Related: Common beneficiary mistakes)
In some cases, a trust can be established to direct life insurance proceeds toward ongoing alimony or child support obligations. (Related: 6 ways to use life insurance for estate planning)
Disability: Illness and injury
Similar to the life insurance questions above, what happens if the alimony payer or primary caregiver in a divorcing couple gets too ill or injured to work?
It’s a situation that happens more often than most people think. Indeed, 1 in 4 adults will be disabled at some point in their working careers.2 So, if you find yourself in the midst of a divorce, make sure that there is adequate protection.
If not, then you may want to take steps to make it part of the divorce decree.
Indeed, some agreements stipulate that if the breadwinning spouse should be out of work, the alimony they pay could in some cases be renegotiated and reduced — or even halted temporarily. Similarly, if the spouse who earns less becomes jobless, the courts could potentially require the working spouse to contribute more during the period of unemployment to help their children maintain their standard of living.
But for longer-term situations, a disability income (DI) insurance policy for one or both parties may be advisable. Such policies help replace a portion of income if someone is unable to work due to a qualifying illness or injury.
Therefore, some divorce agreements can include language that requires the working spouse (or both, if both are working) to maintain DI insurance coverage to protect each other’s interests, with reasonable reserves maintained to pay the premium in the event of a temporary period of unemployment.
If you already have DI insurance coverage, you may want to review it, perhaps with the help of a financial professional, to make sure that you have enough to cover any new obligations as a result of your divorce. (Calculator: How much disability income insurance do I need?)
Retirement accounts: Good divorce split?
In most states, retirement accounts will often be divided as part of the divorce settlement. In certain circumstances and in some states, contributions made or returns earned prior to the marriage may be maintained by each spouse. If you haven’t already, consider consulting a divorce attorney experienced in dividing retirement assets.
“It’s important to understand that retirement accounts governed by ERISA, like an employer 401(k) plan, require a qualified domestic relations order [QDRO] for assets to be divided and transferred tax-free to the alternate spouse,” said Janet Rhodes Friedman, a CFP®, CDFA® of Financial Planning Solutions, LLC in Newton, Massachusetts.
Connect with a MassMutual financial professional
“However, other types of retirement accounts, including individual retirement accounts [IRAs], do not require a QDRO,” she said. Assets transferred 'incident to divorce' may usually be transferred to the other spouse tax-free.
“The rules vary by state, so be sure to understand the laws in your state,” recommended Friedman.
Beyond retirement accounts, you may also be eligible for Social Security benefits based on your former spouse's earnings record if your marriage lasted at least 10 years. (Related: Social Security benefits for ex-spouses)
Health insurance: Covered?
You may be eligible to remain covered under your former spouse’s health insurance after a divorce. If you are not able to maintain coverage under your former spouse's health insurance, it’s best to act quickly to secure new coverage. You may have a limited amount of time.
Important steps are to:
- Understand COBRA: COBRA (Consolidated Omnibus Budget Reconciliation Act) options may allow you to continue your health coverage for a limited time post-divorce. The rules vary from state-to-state and may vary depending on the size of the employer that provides your health insurance coverage. Additionally, you may find that COBRA is more expensive than other coverage options.
- Explore alternative coverage: Research alternative health insurance options, such as private plans or employer-sponsored coverage if available. Even if you missed the open enrollment period with your current employer, divorce is a qualifying life event that allows you to seek coverage outside of the enrollment window.
- Think through dependent coverage: Consider the health insurance needs of your children or other dependents as well.
Estate planning: Update
So many things that seemed clear before and while married may suddenly seem out of focus post-divorce. That’s why it’s critical to take a step back and rethink your estate plan. To get started:
- Consult an estate planning attorney: Seek the guidance of an estate planning attorney to update your will, power of attorney, and health care directives to reflect your post-divorce wishes.
- Revisit name changes: If you assumed your spouse’s name when you married, you can change your name back to your maiden name as part of the divorce process if you wish. Additional paperwork is required. Then make sure all relevant documents are updated with the proper name.
Whether due to oversight or improper planning, estate planning missteps — like leaving an ex-spouse as a beneficiary — can undermine your intent and drastically diminish the financial legacy you leave behind. They can also create added stress for your heirs in a moment of grief. (Related: 6 big estate planning mistakes)
Debts: Who pays?
Common jointly acquired debts include mortgages, car payments, and student loans for children. You may also have credit card debt or outstanding debt secured by your home, like a home equity line of credit.
Ensure that the divorce agreement clearly defines the responsibilities for paying off debts, and work to pay off your share as quickly as possible to help you make a clean break.
“Be sure to include indemnification language in any divorce agreement so as to protect you from liabilities your former spouse may incur,” said Sidgwick.
Child support, alimony, and taxes
Understand the tax implications of child support and alimony payments established in your divorce decree. For this it is usually advisable to consult a tax professional: Talk with a tax professional to understand the tax treatment of these payments as tax laws may change over time.
For example, money paid or received as alimony no longer factors into federal tax liability (after the Tax Cuts and Jobs Act of 2017). This means that one can no longer deduct alimony made under a divorce or separation agreement.
But at the state level, rules vary, which could cause a tax-bracket shift after divorce.
In this regard, divorce also changes your federal tax filing status — from married filing jointly to single or, if you qualify, head of household — which can affect your tax bracket and standard deduction as well.
And also relating to children, if you have college-bound children, keep in mind that divorce can affect financial aid — the FAFSA typically counts only the custodial parent's income and assets. (Related: Students of divorced parents and college aid challenges)
Emergency fund: Rebuild
Often, but depending on the length of a marriage and the state in which the divorce takes place, emergency funds will be split as with other assets. To get a jump on building a financial cushion:
- Set a savings goal: Determine the amount you need in your emergency fund to cover unexpected expenses. Friedman said, “I usually recommend a minimum of 6-9 months of expenses in an emergency fund, ideally even more given the unknown costs of maintaining 2 households.” (Related: Emergency fund basics)
- Automate savings: Consider setting up automatic transfers to your emergency fund to ensure consistent contributions. “I often advise my clients to start saving funds as soon as possible after the divorce, and if possible have a certain percentage of each paycheck deposited into a savings or emergency fund,” Sidgwick said.
Post-divorce budget
Carefully review all your household expenses you experienced as a married couple, and develop new budgets that include all expenses for your two new single-income households.
Setting up a second household will generally be more expensive than your lifestyle while married, especially your household, and living expenses. If your spouse took care of all expenses and tax filings for your household, seek out help from an experienced professional for advice on how to budget for your post-divorce years.
You may also want to apply for a credit card in your own name (if you do not have an individual credit card). And guard against taking on more debt than you can manage post-divorce. This often happens when one party assumes the mortgage on the family home but has a lower income post-divorce.
Women in particular may face unique income and career challenges after divorce, making expert guidance especially valuable. (Related: Financial tips and advice for women in a divorce)
The marital home
This can be the most challenging aspect in divorce, especially if the divorcing couple has minor children. So, it is important that any divorce settlement specifically addresses how it is handled.
For many couples, their home is their primary asset. It is important to consider all aspects of keeping or selling the home to understand what is financially feasible:
- One spouse may keep the house and buy out the other spouse.
- One or both may keep the house for a period of years so that the children can stay in their current schools.
- Refinance the home in one name.
- Sell the home outright and divide the proceeds.
If the home has an outstanding mortgage, the decision can be more complex. It is important to work with a qualified professional or divorce attorney who can develop a range of potential scenarios to consider.
Business buy/sell?
If one of the spouses owns a business, a divorce is typically a triggering event for a buy/sell agreement. That typically means that under the agreement a formal decree of dissolution of a marriage triggers a sale back to the company or to the other owners so the sale proceeds are treated as part of the marital estate and not the business. (Related: What is a buy-sell agreement?)
Conclusion
By taking proactive steps to address often overlooked financial aspects, such as life insurance, disability income insurance, and the other considerations mentioned above, you can help safeguard your financial wellness during and after divorce.
And, as noted earlier but worth emphasizing, be sure to update beneficiary designations on all retirement accounts, life insurance policies, and annuities — these forms override your will and are a common source of post-divorce mistakes.
Remember that consulting with professionals, including financial professionals, tax professionals, and attorneys, can provide invaluable guidance tailored to your specific situation. Prioritizing your financial well-being during this challenging time can set you on a path to a more secure future.
_________________________
Frequently Asked Questions about divorce finances
Q. Do I need life insurance as part of my divorce settlement?
A. Often, yes. Life insurance is frequently used to secure alimony or child support obligations so that payments continue if the paying spouse dies. Many divorce decrees require one or both spouses to maintain a policy with a specified death benefit.
Q. Will I lose my health insurance after divorce?
A. Not immediately. You may be able to continue coverage under your former spouse's plan through COBRA for up to 36 months, though you'll typically pay the full premium plus an administrative fee. Divorce is also a qualifying life event that lets you buy a new plan outside open enrollment. (Related: Retiring early? A guide to health insurance options)
Q. How are retirement accounts divided in a divorce?
A. In most states, retirement accounts are considered marital property and are divided as part of the settlement. Employer plans like 401(k)s governed by ERISA require a qualified domestic relations order (QDRO) to transfer assets tax-free, while IRAs generally do not.
________________________
Discover more from MassMutual …
Divorcing same-sex couples face unique challenges
Social Security benefits for ex-spouses
This article was originally published in October 2021. It has been updated.
________________________________________