| ||||||||||||

With all the talk of a student loan crisis, six-figure student loan debt, and unsustainable student borrowing, it’s easy to wonder if borrowing for college is a good idea.
Indeed, good alternatives exist for the non-college bound. But for many individuals, borrowing for college is the truest path to earning a degree that can spark a fulfilling career and a lifetime of financial security.
The uncomfortable truth is that many students go astray because they don’t consider how much they can afford to borrow for college or how to best use that money. Some end up underemployed and drowning in student loan debt. But it doesn’t have to be that way.
Student debt can be worth it if you...
- Complete the education you borrow the money for.
- Use the borrowed funds to earn a marketable degree.
- Research careers.
- Borrow judiciously for graduate and professional degrees.
Let’s break down each of these guidelines to show how post-secondary school students can make smart borrowing choices for college.
Use student loans to complete a bachelor’s degree
Borrowing to earn a four-year college degree typically pays off, according to research from the College Board, a company that helps prepare students for higher education.1 This conclusion holds true even after considering the time out of the labor force when a student could have been earning money. And it can still be true even if the student borrows the full cost of tuition, fees, books, and supplies.
The College Board’s research uses the weighted average cost of both public and private nonprofit four-year schools, not including room and board, to arrive at a total cost of about $95,000 to earn a college degree. It assumes an average annual interest rate of 6.39 percent on an overall loan and a 10-year repayment period. It found that students will break even at age 34. But that break-even age (age at which cumulative earnings of college graduates exceed those of high school graduates) increases with the amount of time students take to earn their degrees.
It also assumes that by age 34, someone with a high school diploma will be earning $42,300 a year, while someone with a bachelor’s degree will be earning $71,900.
Attending some college without earning a degree helps boost projected income to roughly $47,500 a year. And earning a two-year associate degree is even more beneficial, leading to annual earnings at age 34 of $51,000. But the student who earns the bachelor’s degree is the clear winner, according to the College Board’s findings. By the threshold of retirement age, the student with the high school diploma projects to earn just $51,000 a year, while the one with the bachelor’s degree is earning $90,600.2
“On average, individuals with college degrees experience lower unemployment rates, higher lifetime earnings, and a range of nonfinancial benefits,” the College Board concluded in its study.
It did note that student debt obligations and new technology are adding to questions about the true payoff from college education.
“Shifting public sentiment toward higher education and the rapid advancement of artificial intelligence (AI) are reshaping the broader landscape,” the board noted in its study. “Accelerated AI development raises new questions about changing skill demands, employment stability, evolving workforce requirements, and the growing need for AI literacy and ongoing retraining. These developments underscore the importance of closely examining how postsecondary education aligns with a dynamic labor market.”
Obviously, individual circumstances differ, and no one will exactly match the “median student” used for the study’s findings. However, these numbers can offer students a solid starting point to consider whether student loan debt might be worth it under their unique circumstances. But outcomes depend on choices.
Also, there are ways to reduce the cost of a college education. Starting at a community college and transferring to a four-year school, for example, can significantly reduce total borrowing while still earning a bachelor's degree. (Learn more: Making college affordable)
Earn a marketable degree so borrowing pays off
Colleges and universities provide opportunities to earn a bachelor’s degree in everything from computer science and biochemistry to painting and psychology. Some majors provide a clear and direct path to high-paying, widely available jobs. Others, not so much.
Students can do the research themselves to see which careers are most in demand and offer the best pay, then decide if taking on student debt is worth it.
Then, they can determine which degrees and which schools offer the best return on investment. That’s information that’s especially important to students who will be making loan payments for a decade or more based on choices they make in young adulthood, a time when it can be hard to fully understand the long-term consequences of major borrowing decisions.(Related: What high schoolers need to know about student loans)
“I think that today you really need to look at the possibility of recouping your education costs before embarking on a profession,” said Morris Armstrong, an enrolled agent, investment advisor, and owner of Armstrong Financial Strategies in Cheshire, Connecticut. “The reality is that you may not need an Ivy League education to become a teacher at a local school. That in no way diminishes the importance of educators, education, or related issues,” he said, but you could be well served by an education from a less prestigious school.
Do the research on careers that pay
The federal government’s Bureau of Labor Statistics publishes an annual Occupational Outlook Handbook online. Anyone can consult this handbook to find the median pay and projected demand for workers in almost any occupation over the next 10 years at various levels of education.
Looking at the numbers may confirm some preconceived notions about the viability of some professions versus others.
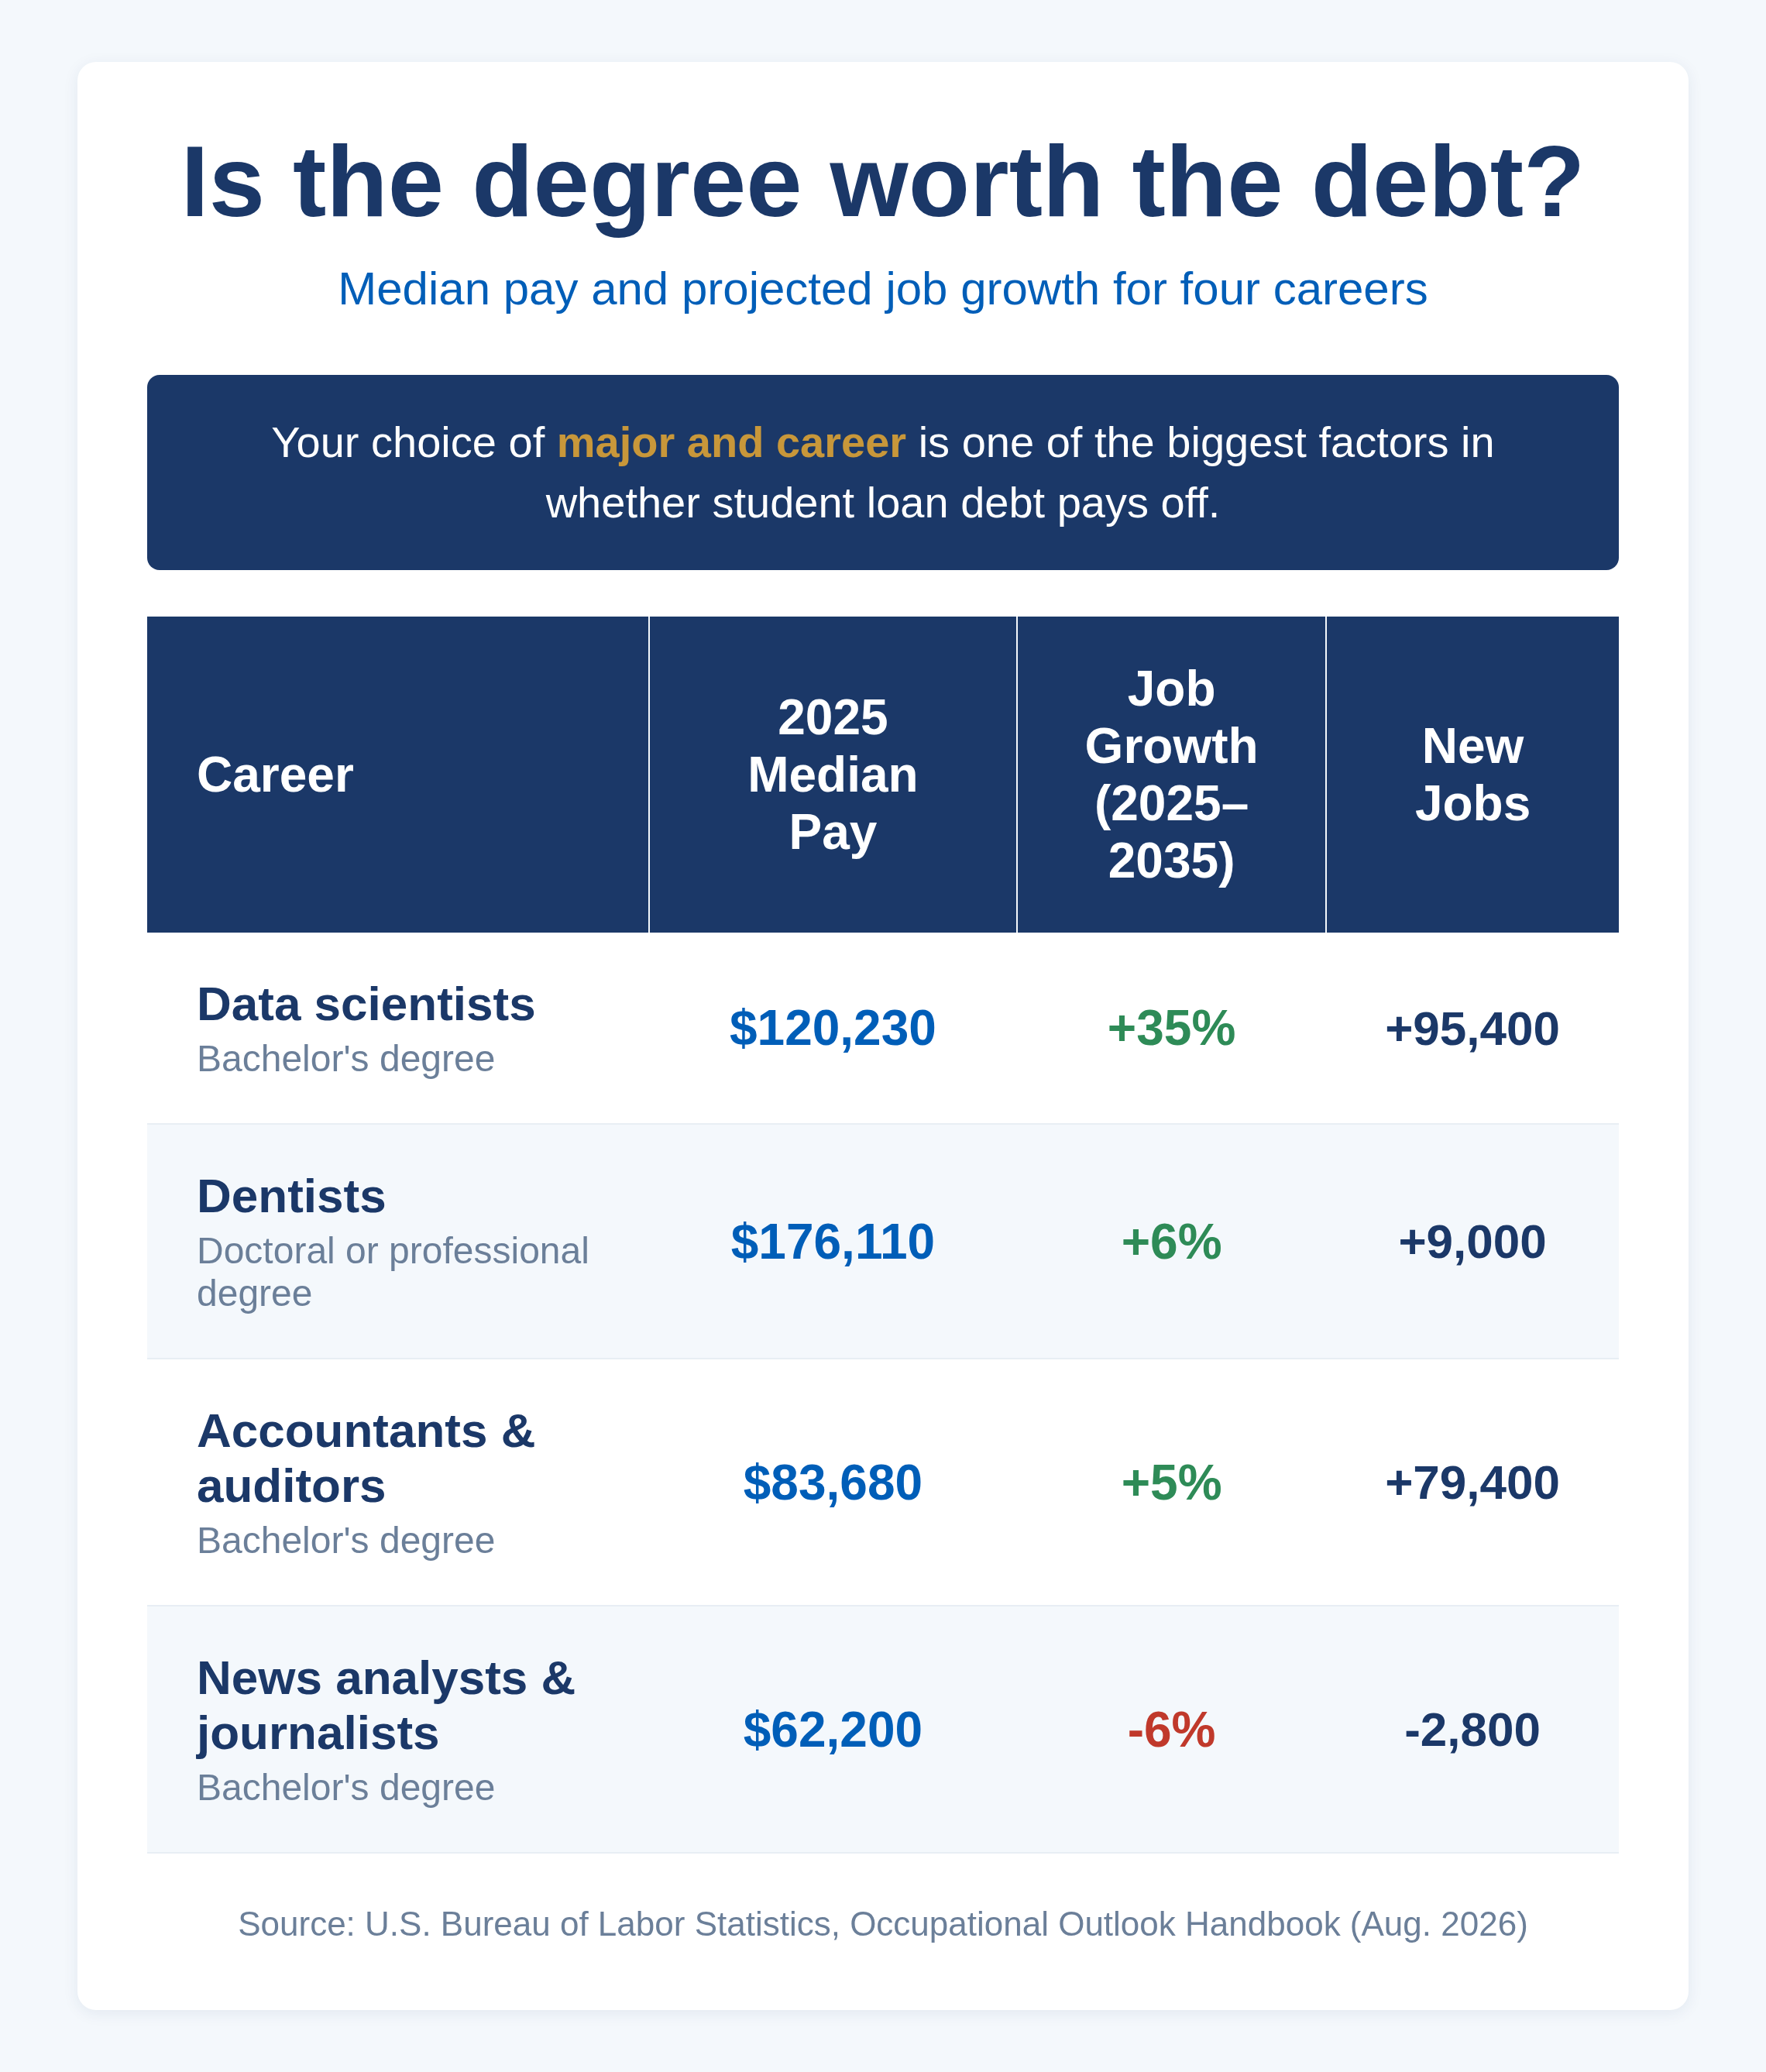
For example, the 2025 median pay for accountants and auditors with a bachelor’s degree was $83,680, the projected annual job growth rate is 5 percent, and the projected number of new jobs over the next 10 years is 79,400.3
By contrast, the prospects are much less rosy for reporters, correspondents, and broadcast news analysts. That category has a median pay of $62,200 per year and a forecasted decline in growth of 6 percent in the number of new jobs over the next 10 years, losing 2,800 new jobs.4
And there can be some emerging surprises. Data scientists, who tend to get involved in growing AI applications, can command a median pay of $120,230 a year with an anticipated job growth rate of 35 percent. About 95,400 jobs are expected to be created in the next decade.5
“Increasing use of information technology, including artificial intelligence, will boost demand for workers in some occupations over the next decade, while other occupations may see their numbers decrease,” BLS observed.
It’s important to recognize that the BLS statistics provide median salaries, which means early career salaries may be lower. And students may want to conservatively assume that they will do no better than the median. But the data can provide a rough basis for comparisons between careers.
It’s also important to note that the government’s findings are only projections and may not come to pass. But it’s worth considering them when deciding how much it makes sense to borrow to earn your degree. (See: How much do I need to save for college?)
This is not to discount the importance of ability and passion. Yes, accountancy may offer promise as a career, but if you are not facile with numbers, it may not be the right choice. Similarly, if you have a particular interest or desire in an area, like art, it may be more valuable to surrender financial potential in favor of personal fulfillment. These are all personal choices, but it’s important to make them fully cognizant of the future implications.
Borrow judiciously for graduate and professional degrees
“Graduate school is the major culprit in burgeoning student loan debt, as there are no limits to federal borrowing like there are for undergraduate students,” said Greg McBride, senior vice president and chief financial analyst for Bankrate.com. “This is where it is easy to rack up six figures of debt that may not translate into a six-figure income.”
Undergraduate students can borrow $5,500 to $12,500 per year in federal Direct Loans, depending on the student’s year of school and dependency status.6 The interest rate on these loans was 6.52 percent for the 2026–27 school year.7
But graduate and professional students can borrow up to $20,500 per year in direct loans, which carry an interest rate of 8.07 percent in 2026-27.
Historically, some borrowers also used PLUS loans to make up any shortfall, although such loans are no longer available to new graduate and professional student borrowers.
.8 (Related: A primer on college financial aid)
Students can perform the same analysis they did as undergrads before deciding to borrow for a graduate or professional degree. They may want to consider questions like:
- Will my degree be marketable?
- What can I expect to earn?
- How long will it take to repay my loans?
- How long will it take to achieve a return on my investment?
- Do I even need to borrow, or could I get an employer to pay for my graduate degree?
For example, consider the average borrowing costs to earn a professional degree in dentistry. For the class of 2025, most students who completed dental school borrowed. The average amount they owed was $297,800, according to the American Dental Education Association.9
The median pay for dentists in 2025 was $176,110, and jobs for dentists are expected to grow 6 percent over the next 10 years, according to the Occupational Outlook Handbook.10 The lowest 10 percent of dentists brought in less than $89,100, and the highest 10 percent brought in more than $337,210.11 Dental specialties can bring in higher salaries but may also entail more debt. And the job can involve more risks than people think. (Related: Dentists and disability)
If we assume an average interest rate of 8.0 percent and a 10-year repayment period, the monthly payments on the average student debt to earn a dental degree will be about $3,624, or $43,488 per year, according to the student loan payment calculator at FinAid.org.12 Obviously those numbers can vary given the volatility in interest rates over recent years.
For some, the cost of debt for a graduate degree may be worth the future earnings potential. There are also other strategies for funding graduate education that don't require borrowing. (Related: Paying for grad school)
And there could be opportunities for refinancing student loans or extending the repayment periods in the future, making the debt load easier to bear. Of course, individual circumstances and future economic conditions could affect the viability of those options, and refinancing federal student loans may result in the loss of certain federal borrow benefits.
With careful planning, student debt may be worth it
Student debt will not be worth it in every situation. Borrowing a large sum and entering a low-paying career will either not pay off financially or take a painfully long time to do so. But the data clearly show that incurring a carefully calculated amount of student debt to earn a marketable degree and enter a well-compensated, in-demand profession is very likely to pay off.
In the end, it’s a personal choice. But it’s an important one, so investigating all the options is key.
_________________________
Frequently Asked Questions about whether student loan debt is worth it
Q. Is student loan debt worth it?
A. For most students who complete a marketable degree, student loan debt can pay off over a lifetime of higher earnings. The College Board's research shows that bachelor's degree holders break even by age 34, even after borrowing the full cost of tuition. (Learn more: How student loans work)
Q. How much student loan debt is too much?
A. A common guideline is to keep total student loan borrowing below your expected annual starting salary. Borrowing more than that can make repayment difficult and delay other financial goals like buying a home or saving for retirement.
Q. Are there alternatives to borrowing for college?
A. Yes. Scholarships, grants, work-study programs, employer tuition assistance, and 529 college savings plans can all reduce or eliminate the need to borrow. Starting at a community college and transferring is another cost-saving strategy. (Related: 9 ways to save on college without a scholarship)
___________________________
Discover more from MassMutual...
6 ways to cut college costs in half
9 ways to save on college...without a scholarship
Biggest college freshman financial blunders
This article was originally published in July 2020. It has been updated.
_____________________________________
1 College Board, “ Education Pays 2026: The Benefits of Higher Education for Individuals and Society ,” April 2026.
2 Ibid.
3 U.S. Bureau of Labor Statistics, “Accountants and Auditors,” Occupational Outlook Handbook, Aug. 27, 2026.
4 U.S. Bureau of Labor Statistics, “News Analysts, Reporters, and Journalists,” Occupational Outlook Handbook, Aug. 27, 2026.
5 U.S. Bureau of Labor Statistics, “Data Scientists,” Occupational Outlook Handbook, Aug. 27, 2026.
6 Office of Federal Student Aid, “How much money can I borrow in federal student loans?” StudentAid.gov.
7 Office of Federal Student Aid, “<href="#how-much">Understand how interest is calculated and what fees are associated with your federal student loan,” StudentAid.gov.</href="#how-much">
8 Note: As of July 1, 2026, Grad PLUS loans are no longer available for new graduate and professional student borrowers, meaning students may need to rely on private loans to cover shortfalls.
9 ADEA, “Educational Debt.”
10 U.S. Bureau of Labor Statistics, “Dentists,” Occupational Outlook Handbook, Aug. 27, 2026.
11 Ibid.
12 FinAid.org, Loan Calculator, accessed Feb. 16, 2024.