| ||||||||||||

Life insurance provides protection, specifically a death benefit that can help your loved ones cope with your loss. But one particular type — whole life insurance — can also serve as a versatile financial asset during your working years and into your retirement.
Whole life insurance offers features beyond protection that differentiate it from other types of insurance, particularly term life insurance or the kinds of universal life insurance typically offered in employer benefit programs. The result is a combination of benefits that include protection, accumulation, guarantees, and income tax advantages.
“Whole life insurance can be used to protect against the potential loss of your income through your working years and protect assets throughout retirement,” noted Jeffrey R. Rotman, a wealth management advisor at Rotman and Associates in Boca Raton, Florida.
Connect with a MassMutual financial professional
Here’s a look at how those features apply to different life stages.
Your working years: Protection and accumulation
Throughout your career, as your family and savings grow, whole life insurance can help with pre-retirement protection and tax-efficient accumulation.
In terms of protection, whole life insurance is a permanent policy, providing a guaranteed death benefit throughout your life.
By contrast, term insurance, a lower-cost life insurance option, often provides protection for a set number of years. And while some term life insurance policies can be converted to permanent life insurance, it comes at a higher price.
Which is another important feature of whole life insurance — premiums are guaranteed at a constant level, and sometimes for a certain number of years or to a certain age, like age 65. With other types of permanent life insurance, the level of premiums can fluctuate.
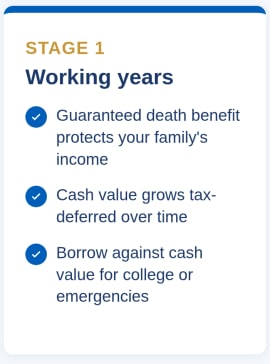
At the same time, whole life insurance builds cash value, which provides a way of accumulating funds on a tax-advantaged basis. As you pay premiums, that cash value increases on a tax-deferred basis at a growth rate that is guaranteed by the carrier.
How fast the cash value grows depends on how quickly premiums are paid.
- Some policies can be paid up with as few as 10 premium payments, and so build cash value relatively quickly.
- Others can use a longer premium payment period, like a pay-to-age-100 premium schedule, and so are slower to build cash value.
Additionally, any dividends paid by the insurance carrier on participating policies can also be used to increase both the life insurance protection and the cash value.1
Building cash value in a whole life insurance policy can help supplement your overall savings plan. Also, you can access your life insurance cash value through distributions or loans for any purpose, like paying college tuition or covering an emergency expense. Distributions under the policy are generally income tax-free up to the amount you’ve paid in premiums.
But there can be consequences if you tap into a whole life insurance policy’s cash value. Distributions and loans can increase the chance that the policy will lapse, reduce the cash value and death benefit, and may result in a tax bill if the policy terminates before the death of the insured. (Related: Treat cash value with care)
“Having this kind of protection through your working years — that is protecting the income capacity of the household — has many advantages,” said Rotman. “As cash value increases in the policy, it can help overcome the unknowns of whether you can access funds when you need them, whether it be for an emergency, house repair, business need, college tuition, or even a car for a student. And, as the cash value of a life insurance policy is generally not a college financial aid disclosure requirement, there is still the potential for need-based financial aid.”
Income options and stability in retirement
The cash value of a whole life insurance policy can be useful in retirement, as well.
Markets go up and down, which means the value of retirement accounts and equity investments can fluctuate. This can present challenges for people depending on those investments for an income stream in retirement.
That’s because taking money from an equity-based retirement account, such as a 401(k) or IRA, during a market downturn will reduce the amount of principal that returns will be based on in the future. That degradation in compounding will likely be particularly troublesome if it happens in the early retirement years. Indeed, one or two years of negative returns early on in retirement can have a significant and damaging effect on the ability to continue withdrawing the same level of income in later retirement years. (Related: Understanding sequence of returns risk)
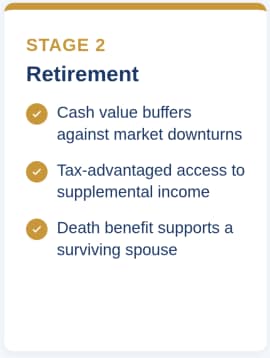
“The cash value can be utilized by the policyowner for income during market downturns to allow investment assets to recover losses before continuing withdrawals,” said Rotman.
Indeed, many people specifically plan to use the cash value component of a whole life insurance policy as a ready reserve of funds for inevitable market pullbacks, allowing time for invested funds to recover. And, as mentioned earlier, cash value can be accessed on a tax-advantaged basis.
Additionally, in the case of retired couples, having a paid-up life insurance policy in place that will pay a tax-free death benefit to a surviving spouse can lessen the worry over how much the couple spends out of retirement funds. Further, death benefit proceeds can help supplement pensions, annuities, and Social Security payments that have been reduced to a surviving spouse.
Senior health needs and legacy planning
Health care costs become a significant concern for many people as they get older, and many try to plan for it. That leads some consumers to consider possible insurance solutions.
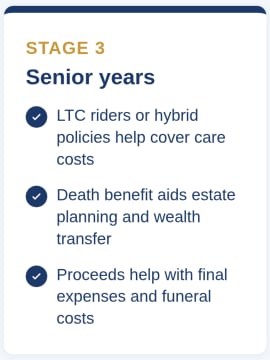
These can range from traditional long-term care (LTC) insurance policies to more innovative mechanisms added to standard life insurance policies.
“More companies are attaching long-term care riders to whole life policies or creating hybrid life/LTC policies,” said Doug Collins, a financial planner at Fortis Lux Financial in New York City. “And these can have lasting value.”
How?
Broadly speaking, traditional LTC policies cover specific care situations, so people wonder if they’ll ever need them. They question whether they’ll ever get any value from it in the long run if they don’t get into a situation where they need care.
So, generally two options have developed in the life insurance industry.
- A long-term care or chronic illness rider added to a permanent life insurance policy, which allows some of the death benefit to be accessed to help with health care expenses, should the need arise. (Related: Understanding riders)
- Hybrid polices structured to combine life insurance and long-term care benefits.
With such policies, taking loans or distributions will reduce the death benefit payable and LTC coverage available. LTC benefit payments will reduce the policy death benefit and cash value available in the overall life insurance policy.
Obviously, the specifics covered and the mechanics of how such polices work will depend on the carrier and the terms of the specific policy. And what solution is appropriate or preferable for an individual will differ from person to person, depending on circumstances and goals.
“Every situation is different,” said Collins. “Consumers seeking primarily life insurance protection with cash value accumulation may consider whole life insurance with a long-term care rider among their available options. Consumers focused primarily on maximizing long-term care benefits may also wish to evaluate hybrid life/LTC products. The advantages of each approach depend on individual circumstances, policy features, and objectives.”
Again, how such riders work and are applied varies from carrier to carrier. Many people opt to talk about the options with a financial professional. At the same time, many also discuss how life insurance can help with estate planning and the management and distribution of assets.
Passing on an estate can involve numerous issues, depending on your personal circumstances and the amount of assets at hand. The strategic use of life insurance can potentially help.
For couples with larger estates, survivorship whole life insurance — which pays out after both spouses pass away — can be a particularly useful tool. (Related: What is a survivorship life insurance policy?)
And, of course, life insurance proceeds can help your loved ones handle your final expenses and funeral costs. (Related: What happens to your debts when you die)
Conclusion
A whole life insurance policy is a valuable life stage tool in addition to a measure of security for your family and loved ones.
Its cash value accumulation offers the ability to supplement your overall savings plan on a tax-advantaged basis. It also allows access to cash value for supplemental retirement income should market conditions turn negative. And it can offer a measure of long-term care protection should the need arise.
Of course, how these benefits come together depends on the specific terms of a whole life insurance policy, and those specifics can differ from insurance carrier to insurance carrier. That’s why it’s important to look at options offered by different life insurance companies. It is also important to consider the insurance carrier itself. An insurance company’s history, structure, and financial strength can all play a factor in how well a whole life insurance policy fits into an individual’s financial plan.
A financial professional can help sort out which life insurance carrier’s whole life insurance offerings may best connect with your own situation.
_______________
Frequently Asked Questions about whole life insurance and life stages
Q. How does whole life insurance help during your working years?
A. Whole life insurance provides a guaranteed death benefit to protect your family's income while building tax-deferred cash value you can borrow against for needs like college tuition or emergencies.
Q. Can you use whole life insurance cash value in retirement?
A. Yes. Many retirees use policy cash value as a buffer during market downturns, drawing from the policy instead of selling investments at a loss. This can help manage sequence-of-returns risk.
Q. When is the best time to buy whole life insurance?
A. Generally, the earlier the better. Cash value takes years to build meaningfully, so starting a policy in your working years gives it more time to accumulate before you need it in retirement. (Related: Whole life insurance coverage: What is best for families?)
_______________________
Discover more from MassMutual …
How to ‘ladder’ life insurance with family changes
Is group life insurance enough?
Whole life insurance: Balancing protection and accumulation
This article was originally published in September 2021. It has been updated.
______________________
1 Dividends are not guaranteed.